Protection for your operations, your employees, and your bottom line
From a single-location shop to a growing team — we compare carriers to build coverage around how your business actually runs.
General Liability
Covers third-party bodily injury, property damage, and advertising claims — often required by leases and client contracts.
- Bodily injury & property damage
- Advertising injury
- Required by most leases
Business Owner's Policy (BOP)
Bundles general liability and commercial property into one cost-effective policy for small and mid-sized businesses.
- GL + property bundled
- Business interruption
- Cost-effective for SMBs
Professional Liability (E&O)
Covers legal defense and damages tied to claims of negligence or failure to deliver as promised.
- Negligence claims
- Legal defense costs
- Common for advisors & agents
Workers' Compensation
Legally required for California employers — covers medical expenses and lost wages for on-the-job injuries.
- Medical expenses
- Lost wages
- Legally required in CA
Excess Liability
Raises the limits on your existing liability policies to protect against a major claim or lawsuit.
- Raises GL/auto/E&O limits
- Protects business assets
- For catastrophic claims
Commercial Auto Insurance
Covers liability, physical damage, and medical costs for vehicles used in your business operations.
- Liability & physical damage
- Medical costs
- For deliveries & client visits
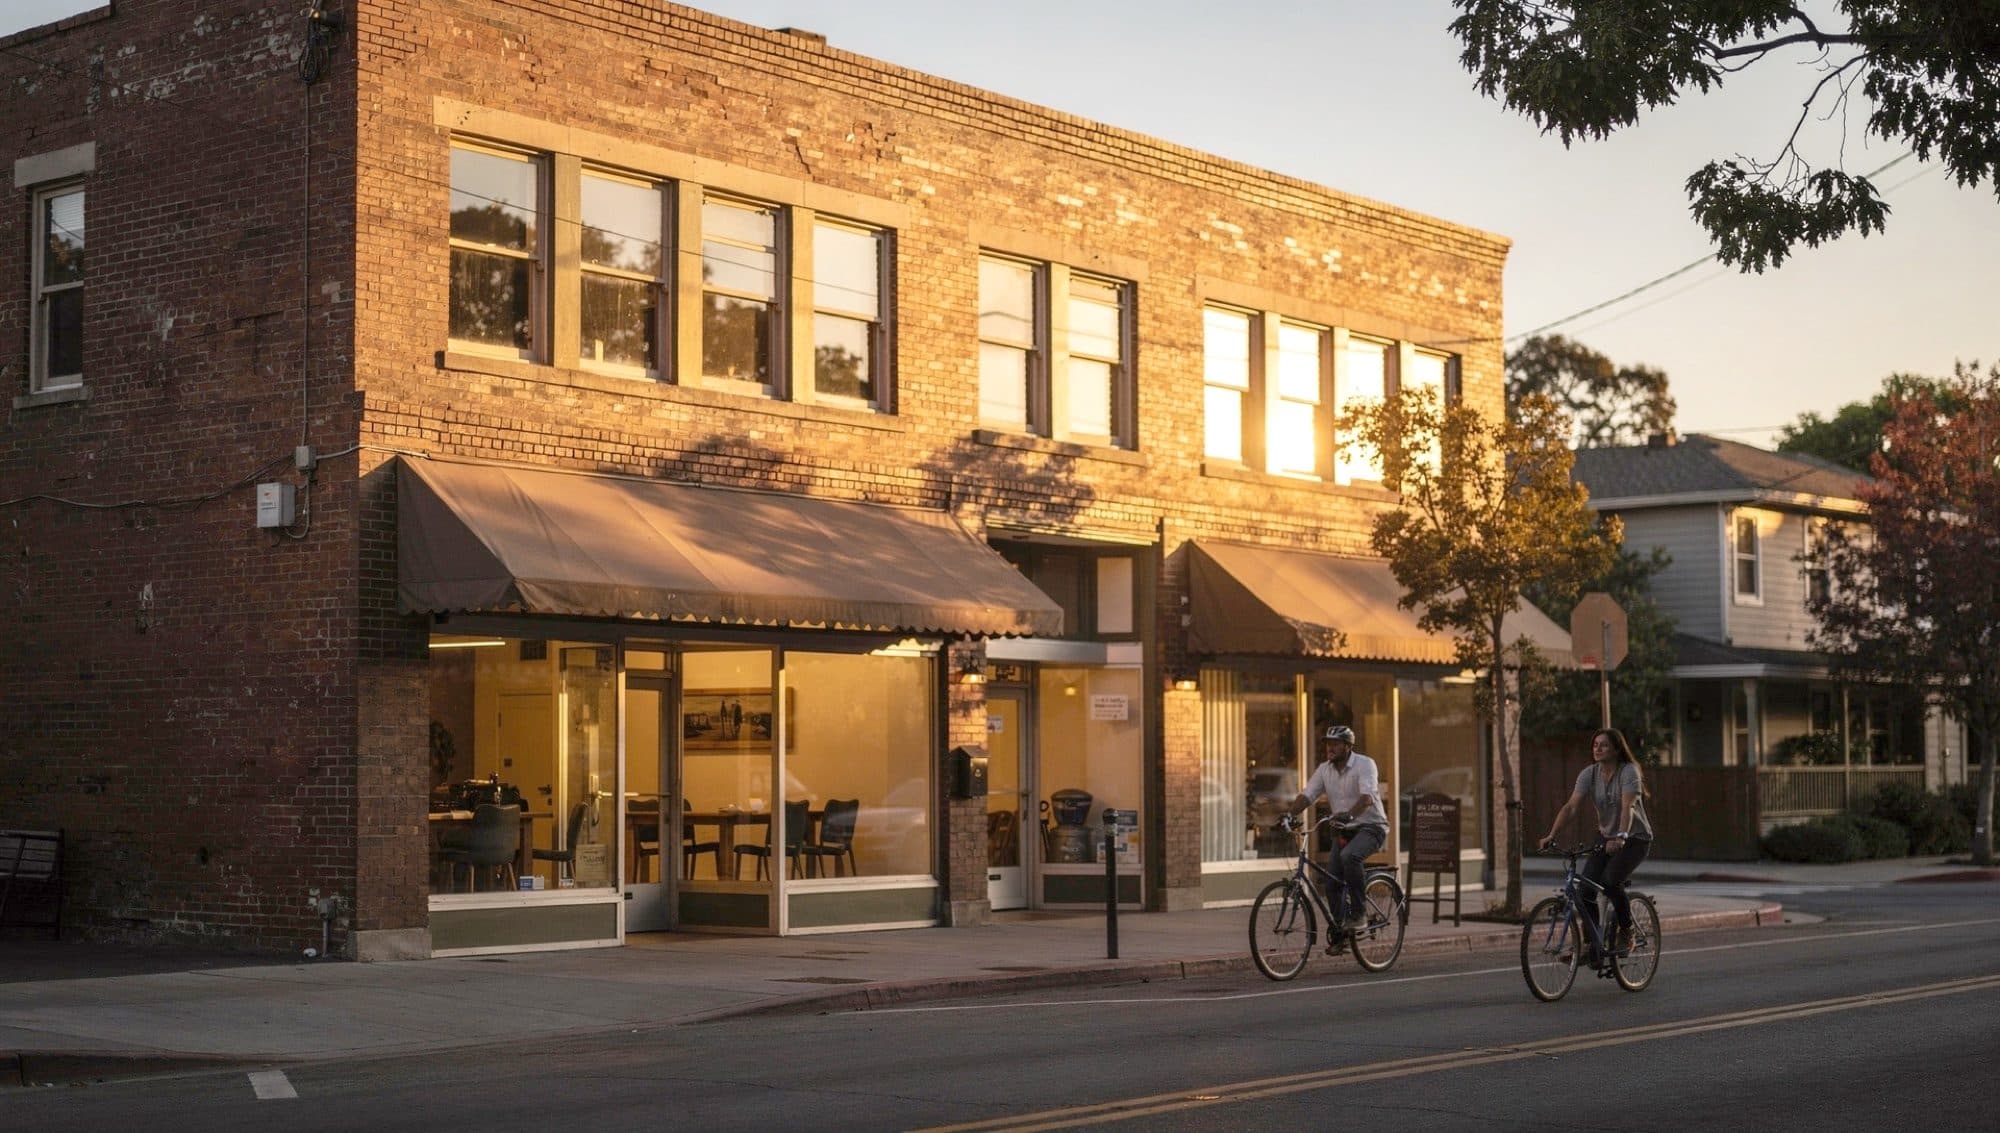
Commercial Property
Protects your building, equipment, inventory, and furnishings against fire, theft, and disasters.
- Building & equipment
- Inventory & furnishings
- Fire, theft & disaster
Cyber Liability
Covers the cost of a data breach, ransomware, or a compromised account — including notifying customers.
- Breach response costs
- Ransomware & extortion
- Customer notification
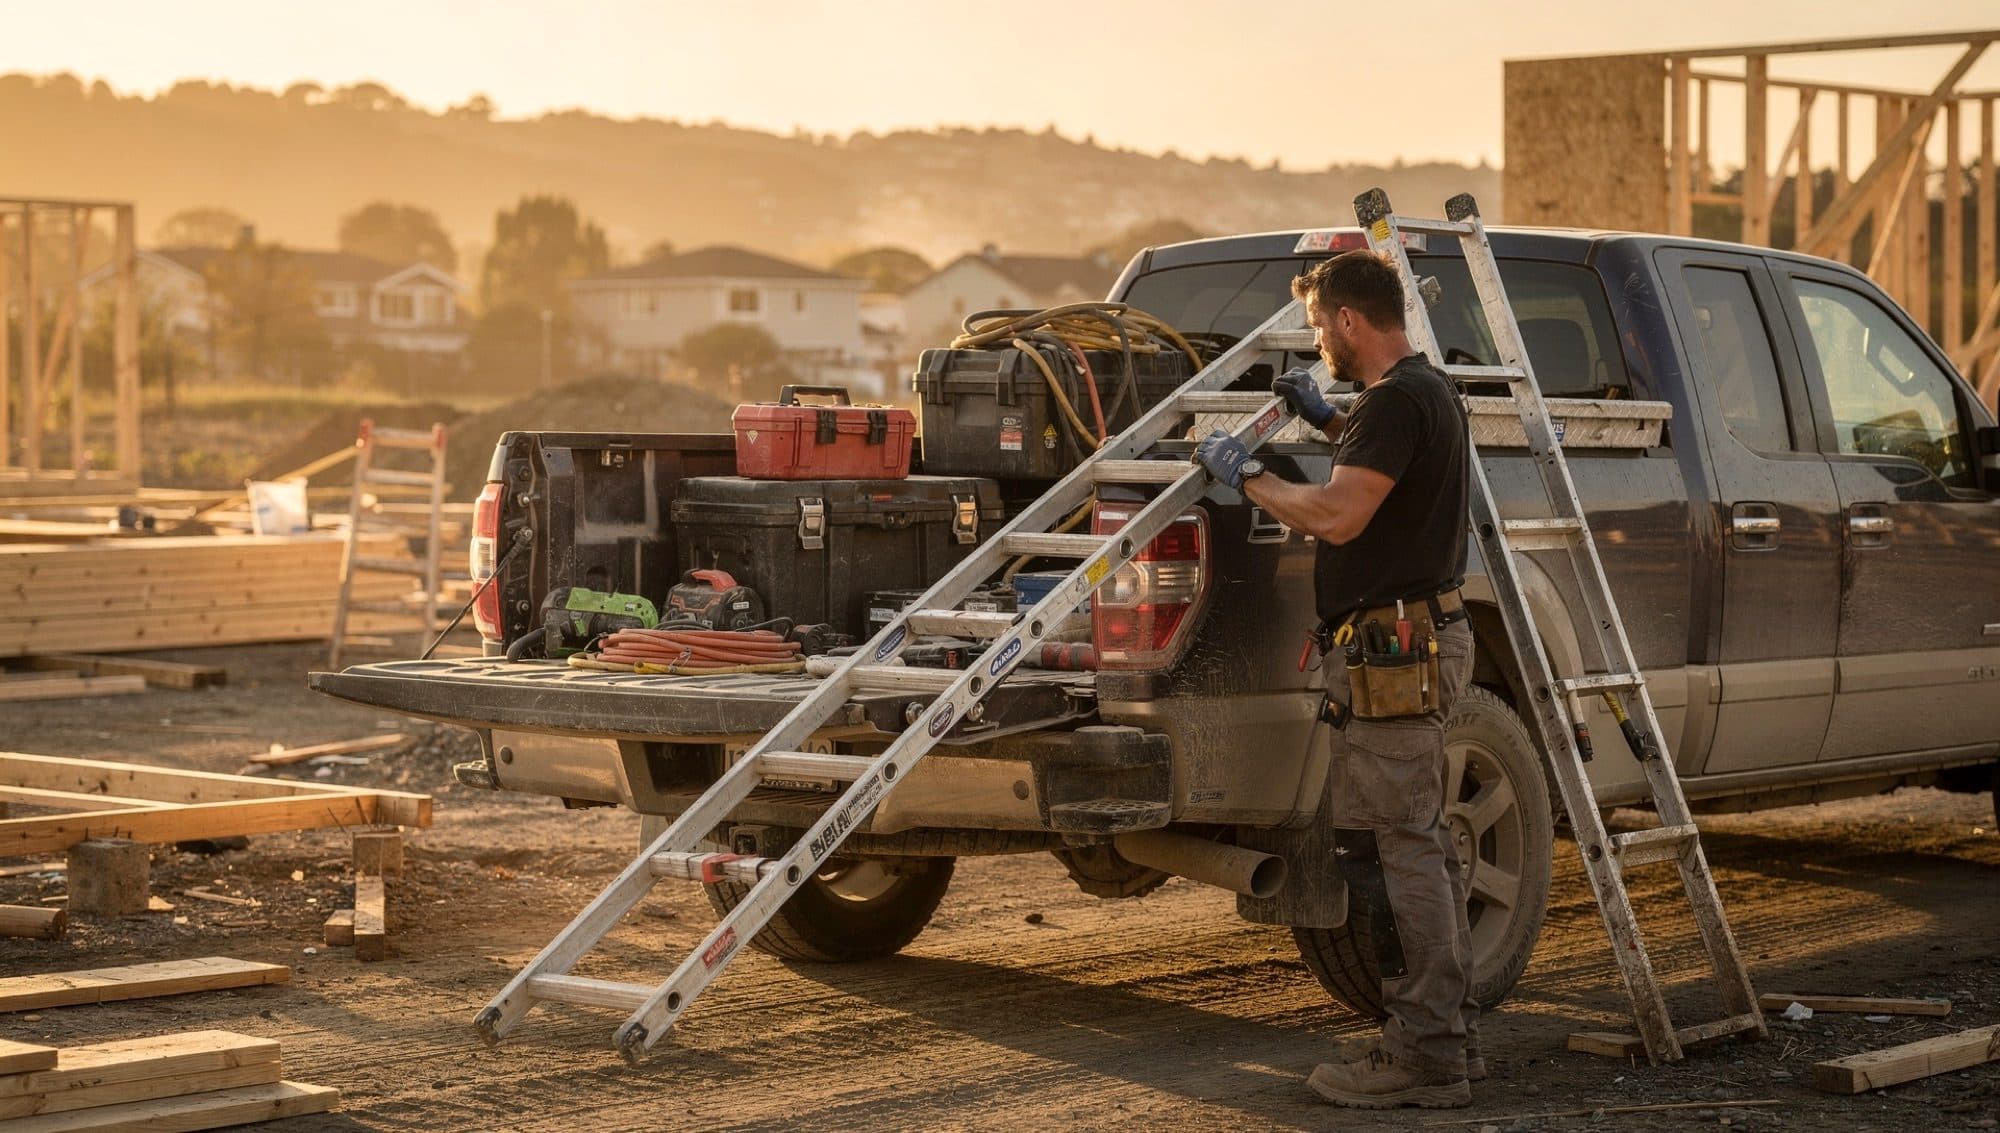
Inland Marine (Equipment & Tools)
Covers tools and equipment while they are in transit or away from your premises.
- Tools & equipment
- Covered off-site
- Theft from vehicles
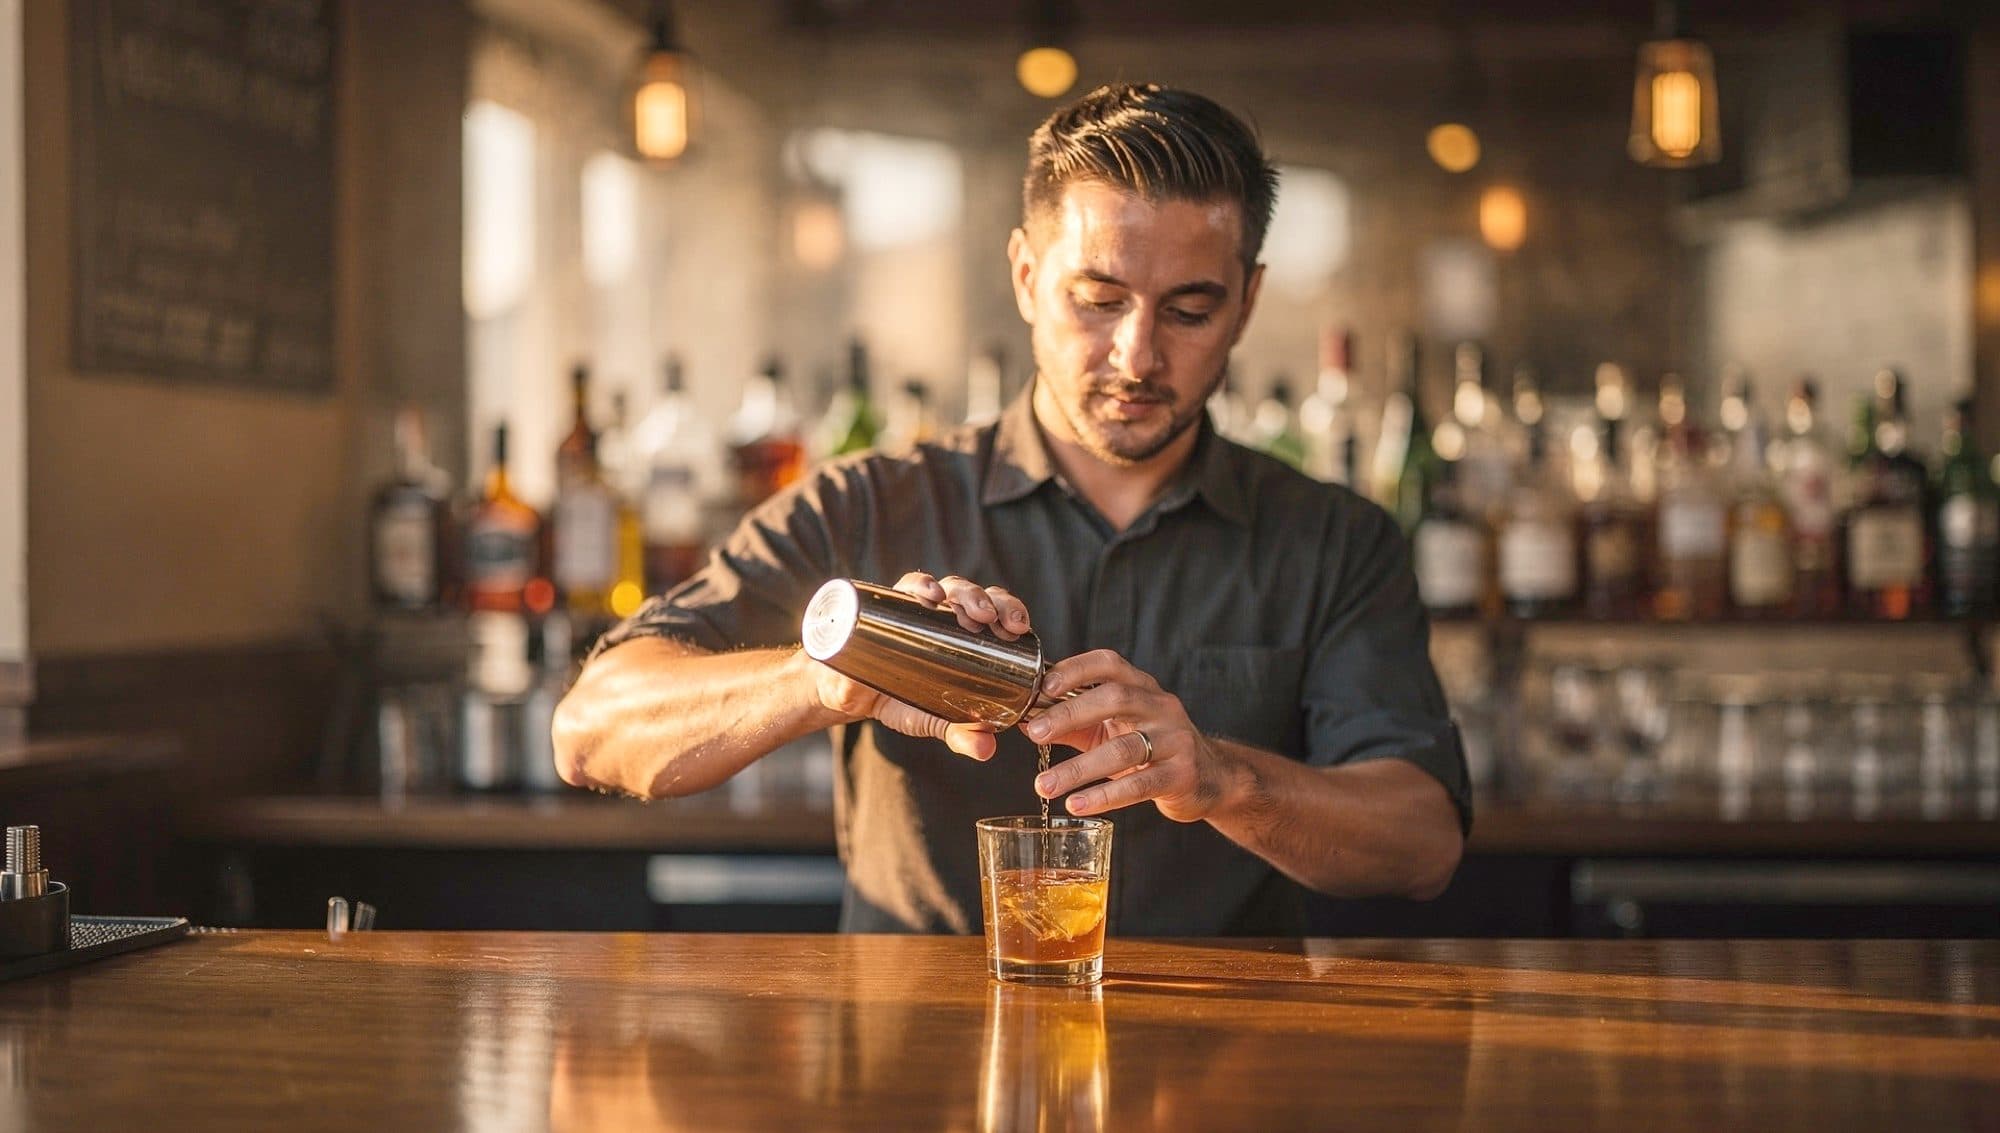
Liquor Liability
For businesses that serve or sell alcohol — covers claims arising from an intoxicated patron.
- Serving-related claims
- Legal defense
- Often required by lease
Employment Practices Liability (EPLI)
Covers claims brought by employees — discrimination, harassment, or wrongful termination.
- Employee claims
- Legal defense
- Wrongful termination
Special Event Insurance
Short-term coverage for a single event — required by most venues before they confirm a booking.
- Single-event coverage
- Venue requirements
- Optional cancellation
Drone Insurance
Liability, hull, and payload coverage for commercial drone work — usually required before a client or venue lets you fly.
- Flight liability
- Hull & payload
- Non-owned drones
Independent means we work for you, not one carrier
Licensed & independent
We're not tied to a single insurer, so recommendations are based on what fits you — not a sales quota.
Multi-carrier comparison
One conversation, several quotes — we do the shopping across top-rated carriers for you.
Personal, local service
Real answers from a real broker in Santa Clara — recognized as a 2025 Women of Impact honoree.